Category: Investing

  • 18. Plant-Based Burgers Made Me Give Up on Picking Individual Stocks

    18. Plant-Based Burgers Made Me Give Up on Picking Individual Stocks

    I followed well-intended burger stock advice from one of my friends, and realized after a stressful period that picking individual stocks is not my strong suite.

    A few years ago, I was having dinner in a restaurant with my friends when plant-based meat was having its moment in the Netherlands. It had crossed over from niche vegan territory into something genuinely cool, at least in my own social circles.

    The marketing slogans were pretty clear, and extremely convincing as well: Better for the planet, better for your health, better for animals. The holy trinity of modern virtue, served with fries on the side.

    Beyond Meat was the name on everyone’s lips and some of my friends were hyping up the rest to give it a try, so I decided to do just that. Admittedly, when my plate arrived and I took that first bite, I was genuinely surprised. It wasn’t beef, sure, but it was actually very enjoyable and I did not feel as sluggish as normal when I powered through a big burger and a big heap of fried food on the side.

    The whole experience had been close enough to make me think this wasn’t a fad, that I’d just eaten a great burger, and that I was genuinely witnessing the future of food in front of my eyes.

    One of my friends, the activist of the group, noticed me nodding approvingly. She knew that I was serious with my investing and had consistently been doing it for almost a year, so she said “You know Beyond Meat is publicly traded, right? You should get in”.

    The Arrogant Investor

    For about a week I was insufferable, because I was genuinely convinced I’d spotted something early. I was going to ride this wave all the way to personal glory and enormous profits. 

    Then the stock started sledding downhill like my niece and nephew do on a snowy day, seemingly without any intention to return to previous levels.

    Beyond Stress

    The whole thing went slow at first. A red day here, a small dip there, nothing major to worry about. But over time it kept going on steadily, persistently, like a balloon losing air so gradually you don’t notice until it’s suddenly sitting on the floor.

    That was the moment when the stress kicked in, hard, and I realized I had absolutely zero clue of what I was doing.

    I didn’t understand Beyond Meat’s financials, couldn’t name their competitors, and had no sense of the margins in plant-based protein or the overall risks the industry faced. My entire investment thesis and due diligence for buying the stock, if you could even call it that, had literally been “tastes great with fries”.

    So I naturally did what any panicking amateur does: I tried to educate myself after the fact. Earnings reports, news articles, Reddit threads, analyst commentary, literally anything that could make me better understand the situation and the company. It was like cramming for a final exam I’d already failed and at this point I certainly wasn’t investing anymore, I was merely firefighting.

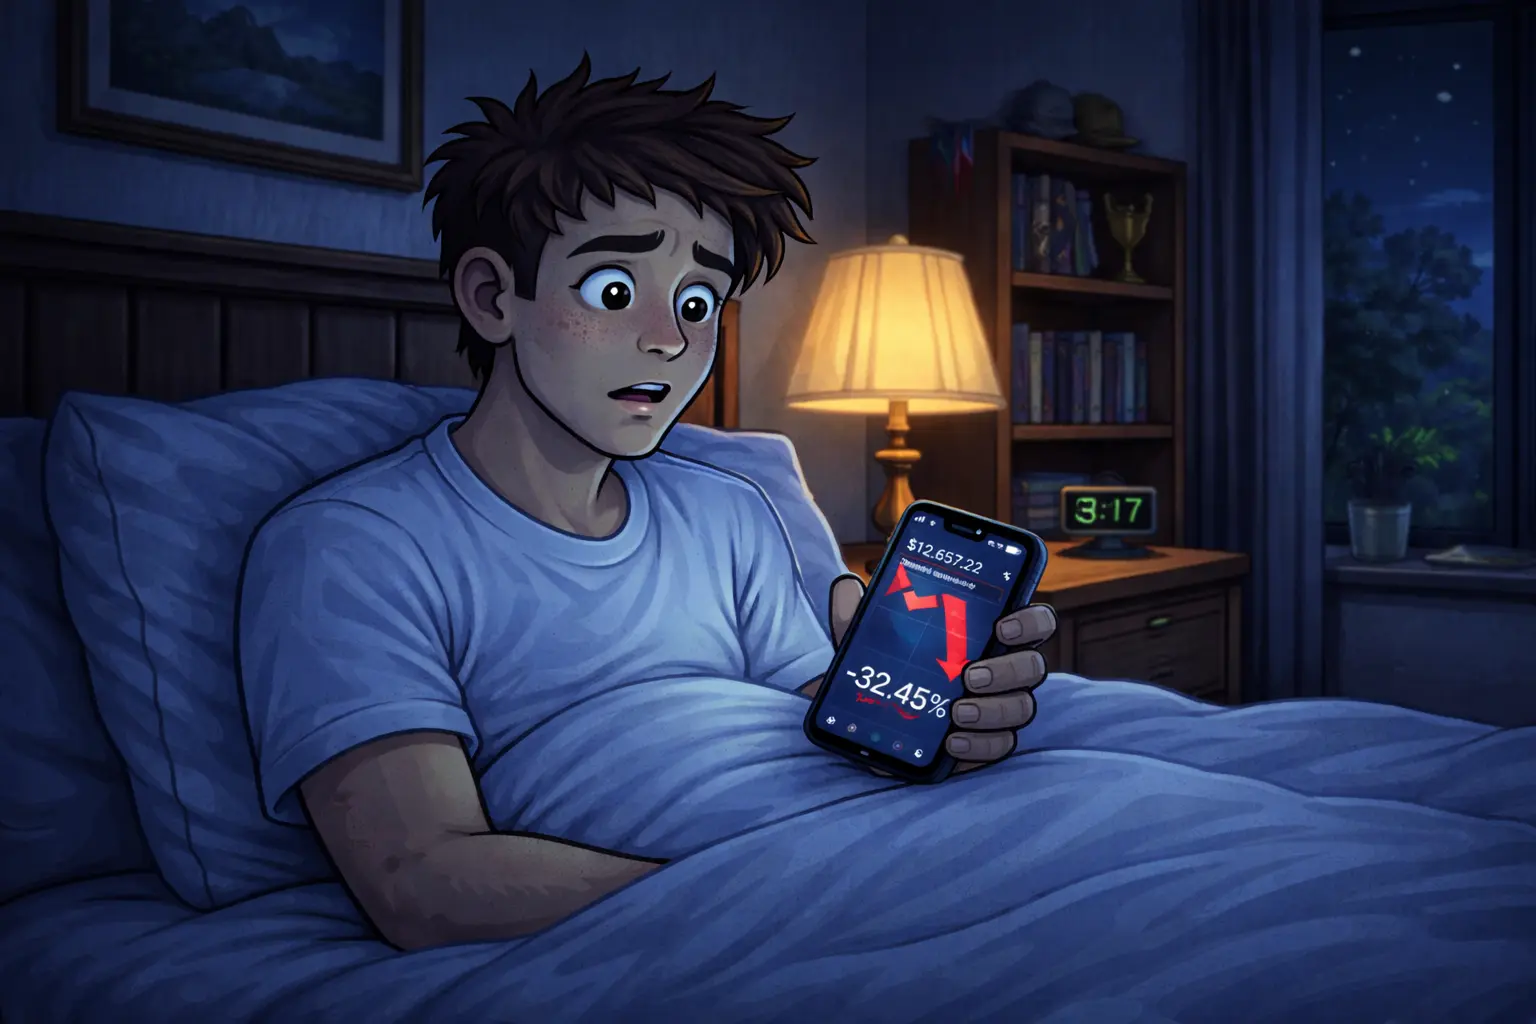
    The stress about the movements of the stock started creeping into everything. I checked the price when I woke up, at lunch, before bed, and anywhere in between. Every dip felt personal, and every piece of bad news like I was being attacked.

    My overall investment portfolio was mostly boring, diversified ETFs, so the position of the stock was marginal compared to the rest. Nevertheless, not being able to explain what was happening to a small part of my portfolio and trying to compensate for that had easily started occupying over ninety percent of my mental energy.

    At some point I simply couldn’t take it anymore. The stress had started distracting from my responsibilities at work, which was where I eventually drew the line that made me sell the whole position without blinking twice. The money I lost wasn’t significant, my portfolio was fortunately still small. The relative percentages of the loss and the overall experience, however, certainly were.

    If You’re Not Edgy, You’ll Be Stressy

    Every investor fantasizes about the hundred-bagger: You find the next Amazon before anyone else does, buy in early, hold on through thick and thin, and someday wake up extremely rich. It’s a very convincing and beautiful dream and it’s probably also, for most of us at least, a trap.

    Because here’s what my Beyond Meat adventure made painfully clear: without an edge you’re not investing, you’re simply making uneducated guesses with your own money. That’s completely fine at a casino, where you know the house wins and you’re paying for entertainment, but it’s less fine when you’re lying awake at midnight while wondering if you’ve just thrown away some of your life savings.

    An edge means you understand or know something the market hasn’t fully priced in. Maybe you work in the industry, have spent years studying the sector, or are able to access information, insights or other resources that most people don’t. When it came down to plant-based burgers, I had none of that. I literally only had a tasty burger and a friend’s well-intended recommendation.

    I also learned that the cost of an investment isn’t just what you pay for it. There can be serious and gradually increasing stress involved if you’re not sufficiently careful. Every hour spent anxiously refreshing prices was an hour not spent on doing my best at work, maintaining relationships, or having proper sleep. Every night of broken rest chipped away at my clarity and judgment in all aspects of life, and by the time I sold my position I’d paid far more in mental energy than I ever did in euros.

    Taking a Different Kind of Risk

    Admittedly, this whole experience didn’t turn me into a conservative investor who just puts his money in a globally diversified ETF and then goes into hibernation until his portfolio has grown. I still tremendously enjoy watching my portfolio, most of the time at least, and still take plenty of risks. But that risk is not consolidated into individual stocks anymore.

    Individual stocks demand an edge I don’t have or take the time to develop. When investing in individual stocks, you’re actively betting that you know something about this specific company that the collective market, with all its analysts and algorithms, has somehow missed. That’s a hard game and, for most people, it’s a losing game. The effort required to find an edge is, in my case, better spent elsewhere.

    If you were to look at my investment portfolio today, you’d see both diversification and a clear focus. It contains a small yet diversified collection of thematic ETFs betting on technological shifts with an intention to significantly change what our daily lives and the core processes of companies are going to look like. It’s a high-conviction, high-volatility approach that would make some people deeply uncomfortable.

    But there’s a crucial difference between the risk associated with my current portfolio and the risk I was facing when investing in plant-based meat.

    When I own a thematic ETF, I’m investing in a generic direction, not on my ability to pick the winning horse. This approach has been one of the reasons why I’ve managed to ride a significant portion of the AI wave with decent results. I don’t need to know which AI company will dominate the next decade, I just need to believe that AI matters. That’s a belief I can verify every day at work, where I watch whole departments restructure their entire workflows around it. I’m not guessing about a single company’s execution, but I’m observing and following a shift that’s already happening in front of my own eyes.

    Thematic ETFs ask for conviction in a trend and the patience to hold through volatility, whereas a single stock usually requires you to be smarter than the market. Following a thematic ETF strategy just requires me not to panic when the market gets nervous, which so far seems to suit my personality reasonably well.

    Good Sleep is the Best Return on Investment

    Have my current approach and portfolio made me a good investor? I honestly don’t know. The overall numbers have been good, probably a couple percentages above the market average, but I’m not sure that’s the point anymore.

    What I know is this: I sleep well at night and I don’t check market prices compulsively anymore. When markets drop I feel something closer to curiosity than dread, and occasionally even excitement about buying cheaper. My portfolio works for me instead of against me, and I’ve had a couple of moments already where I put in money on what in hindsight turned out to be best-buy moments.

    When I think back to that dinner and the plant-based burger, I can finally laugh about it. I walked in hungry and walked out convinced I’d found my ticket to early retirement. But in the end, I probably found something much more valuable: the knowledge that the best portfolio isn’t the one with the highest ceiling, but the one I can actually live with.

    Beyond Meat cost me money, sure, but the stress it bought me was the real price. And once I understood that, I stopped trying to pick stocks and started building something I could hold comfortably without losing my mind.

    Honestly, sometimes the best return on investment isn’t the money. It’s a good night of sleep while your money keeps working for you through the highs and lows.

  • 15. My Well-Intended Advice Nearly Bankrupted My Best Friend

    15. My Well-Intended Advice Nearly Bankrupted My Best Friend

    Even great money advice can have disastrous consequences when applied in the wrong context. My advice once got my best friend in financial trouble, and it took a new mental model to fully understand why.

    My best friend was buzzing. I’d just explained to him how I was investing: ETFs, long-term thinking, compound growth, the whole shebang. He loved it. “I’m starting this month” he told me, and I enthusiastically showed him how to do so.

    I should’ve asked more questions like “Do you have rent covered for the next six months?” or “What happens if your car dies next week?”, but I didn’t. The advice I’d given him was solid, right? Everyone says to start investing as early as possible, and the internet is full of inspirational quotes backing this up: “Time in the market beats timing the market”, “Rachel started with $50 a month at 20, so Ross with $500 at 30 will never surpass her”.

    The worst part? Since the money hadn’t grown, he’d been forced to withdraw less than what he started with. Fortunately his bank didn’t have withdrawal fees on ETFs, but the whole situation gave him this sinking feeling that he was doing something fundamentally wrong.

    Except he wasn’t doing anything wrong, I was. I’d given him advice that had worked perfectly for me, and then watched it completely threaten his own financial situation.

    The Part I Missed

    So what did I miss? Turns out, the advice to “start investing early” isn’t inherently bad. It’s just not universal.

    It implicitly assumes you’ve got money sitting around that you won’t need for years. It assumes that rent is covered, that groceries aren’t scary, and that if your washing machine explodes tomorrow you’re annoyed but not financially ruined.

    When I personally started my investment journey, I’d built a small but important savings buffer to give myself some peace of mind first. Not because I was some financial genius, but because my risk-averseness made me accidentally stumble into it in the right order.

    My friend didn’t have that foundation, I’d simply taught him how to start building wealth without first checking if the ground was actually solid.

    And that’s when it hit me: all financial advice isn’t inherently good or bad. It’s contextual. And context, when money is involved, is pretty much everything.

    Enter The Wealth Ladder

    A couple of months after that awkward portfolio update, I stumbled on this book called The Wealth Ladder by Nick Maggiulli.

    I devoured it in two days, because from the first pages it felt like someone had just handed me the instruction manual to something I’d been winging it without. It was genuinely insightful, which is rare for most personal finance content I see nowadays, and it perfectly explained the root cause of the shitty situation I’d helped my friend end up in.

    The book splits your liquid wealth into six levels, each a 10x jump from the one below:

    Level 1 (€0-€10k): Survival mode, living paycheck-to-paycheck. You’re covering rent and buying groceries, but financial setbacks have a significant impact. You want to get out of it as soon as possible, because your financial situation could have long-term health implications. At least, that’s how I personally experienced it.

    Level 2 (€10k-€100k): You can finally breathe, financially speaking. There’s a buffer to handle financial setbacks, and groceries aren’t scary anymore. Focusing on your career means income growth, some of which you can maybe start putting aside for the longer term.

    Level 3 (€100k-€1M): Day-to-day finances aren’t stressful anymore, meaning your money has enough mass that it increasingly starts working for itself. Meaningful income growth might actually be found outside the career ladder, because making vertical steps becomes increasingly difficult. 

    Levels 4-6 (€1M+): These levels have great descriptions in the book, but I can only imagine what these look and feel like. I’m not there, so I won’t put them in a personal story like this if I haven’t validated them for myself.

    What matters most about these levels: the problems and possibilities are completely different at each one. Advice that works at one level can wreck you at another. My friend was at Level 1, while I’d given him Level 2 advice. No wonder it went sideways.

    And that’s where I got lucky myself. Not because I made a ton of money or had some brilliant strategy, but because I stumbled through these levels in roughly the right order without even knowing there was a sequence.

    My Own Climb

    I graduated university with exactly €0 to my name. Not “close to nothing”, actual zero. I moved back in with my parents after landing my first job, since that was the only way I could save anything on my below-average salary. I lived like a broke student who’d forgotten he graduated. Six months of extremely aggressive saving later, I hit Level 2. The big freedom at that point? I stopped checking grocery prices during a period of rapidly rising Covid inflation. That’s it. Nothing glamorous, but very meaningful.

    Then my now ex-girlfriend and I moved in together. We renovated the place, bought furniture, and made it a home. And my savings? The majority of it gone, since renovations and furniture add up fast. Back to Level 1, living paycheck to paycheck. Stuck there, too, because my income was exactly covering my lifestyle.

    Then I switched employers, negotiated well, and got a salary bump of more than 50%. Saving finally became an option again. I rebuilt my buffer and started my investing journey, although still with relative small amounts. Enough to get used to the idea, but not enough that I’d panic if I needed it back. This time, Level 2 stuck for good.

    My relationship eventually ended (with the biggest financial mistake of my life as collateral damage), and although I stayed in Level 2, it did end with me moving back in with my parents again. Overnight, my living costs dropped, savings rate exploded, and investing became a habit instead of a sacrifice I had to consciously think about.

    That was when I eventually hit Level 3, where I am now. A comfortable salary, a strong savings buffer, a six-figure investment portfolio that grows significantly even when I don’t touch it, and the mental peace, financial space and time to start this blog. Not to get rich, but to do something that 100% personally satisfies me without compromise.

    Looking back, I did almost everything right by accident. I got out of Level 1 as fast as possible (twice), built a buffer before investing, only invested money I wouldn’t need for some time, and let my career growth raise my baseline income before inflating my lifestyle.

    But my friend? He effectively tried skipping Level 1 by investing for the long term while still figuring out how to create the financial space to actually allow it.

    And that was the entire difference, nothing more.

    The Filter

    So, does the wealth ladder deliver any value beyond understanding what went wrong? Absolutely. If you’ve read carefully by now, you’ve probably already deduced that it’s also a perfect framework to filter the metaphorical firehose of financial advice, whether it’s online or from people around you.

    When you scroll past a YouTuber explaining tax optimization strategies, you can ask: Which level is this for? My guess would be probably Level 4 and beyond, so best to skip it if you’re at Level 2.

    When a blogger talks about building an emergency fund, you recognize that it’s Level 1 advice. If that’s you, pay attention. If you’re already Level 3, you’ve probably already got a significant buffer and your biggest emergency is actually making sure you use it in a meaningful way.

    When a TikToker brags about their €450 a month side hustle, you see it for what it is: maybe inspirational for Level 3, irrelevant for Level 5, and potentially harmful for Level 1 and 2 since time is better spent there on building or increasing stable income.

    Good advice can destroy you if the timing is wrong. The wealth ladder doesn’t tell you how to get rich, it simply tells you which advice to ignore right now. And my best friend? He’s fine now. He took time to build his buffer first after nearly getting in financial trouble, and only then restarted investing. Same advice, different timing. And this time it worked.

    Sometimes the best financial move isn’t doing more. It’s recognizing where you actually are, and doing what matters there first.

  • 4. Useless Midnight Portfolio Checks Have Made Me a Better Investor

    4. Useless Midnight Portfolio Checks Have Made Me a Better Investor

    My first year of investing: down 10%, checking my portfolio at 2am, and convinced I was doing everything wrong. Turns out, I was doing everything right and simply learning to stay consistent.

    My phone screen lit up the dark bedroom. 2:17 AM.

    There’s something almost funny about staring at a red number on a screen at midnight, knowing the market is closed, knowing absolutely nothing will change until morning, but still not being able to put the phone down.

    Nothing had changed since I checked before dinner, or before bed, or twenty minutes earlier when I told myself that one would really be the last. The numbers would be the exact same shade of red they’d been all day.

    Welcome to New Investor Syndrome, a very familiar phenomenon for everyone who’s ever put real money into the market for the first time. The strange magnetic pull toward information you know won’t help you, delivered by apps that definitely shouldn’t be opened at midnight. 

    Although I seriously did my due diligence before starting my investing journey, no one could’ve prepared me for the sheer obsession of seeing my own money move in real life. Fortunately, once the obsessive checking phase faded, I realized I came out of it a much better investor than before.

    Podcast Preparations

    I didn’t start my investment journey the moment I graduated university and received my first salary. Instead, I spent almost a full year listening and learning about investing.

    A close friend had recommended a Dutch podcast, Jong Beleggen, and its premise was brilliant: a young entrepreneur had just sold his company and was investing the proceeds in real-time, documenting every decision and every feeling along the way. Each episode covered some of the basics of investing, the state of his portfolio, and most importantly, how the inevitable volatility actually felt from the inside.

    I listened religiously while commuting, cooking, and doing laundry. It became the background noise of my daily life and slowly, without realising it, I was getting an honest picture of what investing actually looks and feels like: the anxiety when numbers turn red, the temptation to lock in losses, and the discipline of staying still when every instinct tells you to act.

    One episode really stayed with me. The host’s portfolio had dropped several thousand euros in a single week, and his social circle had sent him some pointed messages about the wisdom of his choices. But when he talked about it on the podcast, he just sounded… fine. Not thrilled, obviously, but calm and grounded. “This is what markets do”, he said. “I’m not selling”.

    The listening gave me the confidence to make a start with investing. I understood the basics, and if the podcast host could handle thousands disappearing without losing his composure, I could probably see hundreds evaporate without losing mine.

    Bearish Beginnings

    I finally opened my investment account in April 2022, once I had enough financial breathing room to commit €500 a month without touching my emergency fund. The plan was straightforward: a globally diversified ETF as the core and a couple of thematic ETFs for personal interest, followed by a lot of patience.

    The market, however, had other ideas.

    My portfolio immediately started swinging in ways I hadn’t expected, even after that year of preparation. Three months in, I was down 10%. Five months in, somehow up 15%. By year’s end, 11% in the red. I’d started my investing journey right at the beginning of a bear market, excellent timing if your goal was to be immediately tested.

    It was here where the year of listening earned its keep. Because when the first 10% drop arrived, I could listen in real time how the podcaster reacted to the events. He’d lost thousands and hadn’t sold, whereas I’d only lost hundreds.

    It was a welcome perspective on events, because I’d become so obsessed with watching my money move that I probably would’ve made some seriously unwise actions without it.

    The Obsessive Checking Phase

    My portfolio showed more mood swings than a teenager on Red Bull, and I was watching it like a social media feed. Morning checks, lunchtime checks, before-bed checks, and the occasional midnight checks just to confirm that nothing had changed since the before-bed checks.

    The temptation to sell was absolutely there, and I actually came very close on multiple occasions. That voice telling you to sell now, stop the bleeding, wait for things to stabilize, and then get back in at a better price, is a very persuasive one. It sounds so reasonable when your portfolio is down and you’re consistently being confronted with red numbers.

    And slowly, over time, something shifted. The red numbers started feeling less like catastrophe and more like information. Uncomfortable information, sure, but information that didn’t require a response because the numbers didn’t matter until years later anyway. The market simply did what it did. My job was to just keep investing and otherwise leave it alone, staying disciplined even when my instincts screamed to tinker. 

    I’m happy I stayed the course, but it wasn’t until late 2023 – one and a half years after I started my investing journey – that my portfolio stayed green for good. Looking back, it was exactly the gradual adaptation of seeing red without reacting that had kept me invested long enough to get there.

    Becoming a Proper Money Stoic

    In hindsight, all the money invested until I left the red numbers for good was learning money. All those days with red numbers weren’t losses, they were lessons I was paying to learn. Lessons about how I actually handled volatility and pressure, when it was my own money on the line and my brain was making very compelling arguments why selling was the best thing to do. They’re the kind of lessons most personal finance content will never be able to prepare you for. Instead, you have to pay for them with your own money, emotions, and sleepless nights.

    What those months listening to the podcast and staying the course quietly built, I didn’t realize until much later, was a more stoic relationship with money. The ability to feel the anxiety, observe it clearly, and deliberately choose not to act on it. I could handle volatility with my own hard-earned money, not theoretical calculator money from a practice portfolio. When I got a nice promotion at work, the confidence that came from that eventually allowed me to comfortably double my monthly contributions without thinking twice. Without having paid that learning money upfront, I don’t know if I ever would’ve been able to do that.

    And that’s the education no personal finance content mentions when it tells you to start investing early. Your first year isn’t about the returns at all. It’s about finding out who you are when your money is doing things that are completely out of your control.

    Turns out, I was someone who obsessively checked his portfolio at midnight and still didn’t sell.

    I’ll take that.

  • 3. An Xbox Game Taught Me the Principles of Investing and Early Retirement

    3. An Xbox Game Taught Me the Principles of Investing and Early Retirement

    Fable II taught me investing lessons long before real life did: buy assets, let money work for you, and build the freedom to play on your own terms.

    When I started my investing journey, the numbers were small at first. But after years of consistent investing I watched the growth gradually starting to accelerate, and something about that felt weirdly familiar. I couldn’t quite place it at first, and that feeling of familiarity kept nagging at me.

    Maybe you’ve experienced something similar as well. That weird recognition when something you learned as a kid suddenly starts making sense in your adult life. Like muscle memory, but for concepts instead of movements.

    It took me a few weeks before it clicked: I’d experienced this exact investing thing before, years ago, in a video game where I spent as much time kicking chickens and flirting with villagers as actually saving the world.

    That game was Fable II, and I still love it today. Not because it tried to teach me anything about money, but because it gave me a gaming experience that I’ve never been able to get anywhere else.  

    It also let me unconsciously experience how investing works and feels, long before I ever opened my first investment account. Not through lectures or tutorials, but by letting me become a landlord in a medieval fairytale world drenched with British humor and sarcasm.

    Why a Game From 2008 Still Feels Like Home

    Fable II is a fantasy RPG set in the fictional world of Albion, and was released in 2008. It is absurd, charming, and still one of my favorite games of all time, which is why I replay it virtually every year. Not because the graphics hold up or the combat is revolutionary, but because there’s something genuinely cozy about it.

    If you’ve never played it: imagine Monty Python meeting The Sims, and every NPC having a strong British accent that makes even insults sound charming. If you did play it, you already know exactly what I’m talking about, and you’re probably remembering your own ridiculous adventures in the game.

    Most RPGs make you the Chosen One from the start, but Fable II does something entirely different. Sure, you’ll save the world at some point, but first you need to eat, pay rent, and prove yourself. And maybe marry that sexy shopkeeper you’ve been flirting with, even though you already have a spouse in another village.

    It’s that mix of epic quests, mundane choices and absurd twists that makes the world feel lived-in. You’re not just watching Albion’s economy, you’re actively participating in it. Combine that with golden-hour lighting and a world you can fully explore in 40 hours, and you’ll get something rare: a game that feels like a warm hug, even when you’re fighting trolls.

    Working Or Sleeping For Your Money

    The game doesn’t hand you a lot of money when starting your journey. You’re a hero, sure, but you’re also broke. You need gold to survive.

    The obvious route? Side hustles like blacksmithing, woodcutting or bartending, where your earnings depend on your skill at mashing buttons. Then there’s the hustler approach: buy items at one shop, and then sell them at another for profit. Or you can gamble if you’re desperate, though just like in real life there’s a big chance you’ll end up with empty pockets — the house always wins in the end.

    All of these activities can make you money, but they also require you to actively grind for hours on end.

    As for spending? You can buy better weapons and clothing, gamble it away, or buy properties. And that’s where investing suddenly comes into play.

    When I checked my gold balance later, it had grown. The stall had been collecting rent every five minutes of active playtime. Not much, but it was accumulating without me doing anything. 

    Wait. Earning money while not actively working? That caught my attention.

    If you’ve ever played a game with any kind of economy system, you probably know this feeling. That moment when you realize you’ve stumbled onto something that breaks the game’s intended progression. It feels like cheating, except it’s completely allowed.

    From Broke Blacksmith to Medieval Mogul

    So I bought another property, and then another. The rent from my first properties helped me afford bigger ones, each purchase making the next one easier. I wasn’t just collecting rent anymore, I was actually watching my money compound in real-time. Every gold coin went straight back into buying more properties, and property five came faster than property two, while property ten came faster than property five.

    Before long, I owned dozens of properties across Albion: market stalls, houses, shops, taverns. And eventually, the largest property in the game: a castle worth one million gold. That number felt impossible when initially blacksmithing for 50 gold at a time, but here it was. Not because I was the strongest fighter, though I became that too once I could afford all the strength boosting potions, but because I’d figured out that passive income beats active grinding.

    Properties generated rent whether I played or not, and they also went up in value as the town economy improved. The implicit lesson was clear: buy productive assets, dump the profits back in, and let time do its magic.

    Eventually, gold wasn’t a constraint anymore and I could retire myself from actively working for it. The result? Doing quests because the stories were interesting, not because I needed the reward. Exploring because I actually wanted to get to know the world better, not because I was hunting treasure.

    This financial freedom and “early retirement” didn’t come from buying the newest shiny sword, it came from owning the blacksmith that sold it to every other wannabe hero. And that feeling, even in-game, was surprisingly real. Not because pixels mattered, but because the progression felt earned and I could watch the growth happen.

    And here’s the coolest part: even when my mum angrily barged into my room and unplugged the Xbox after I’d been playing for hours, my character kept earning gold. When I finally returned the next day, after dutifully receiving my lecture about screen time, I’d still made more of it.

    When My Video Game Strategy Became My Investment Strategy

    Fast forward a decade. I’m in my mid-twenties, opening my first investment account and buying ETFs for the first time.

    If the companies in those ETFs paid dividends, they got automatically reinvested. That was exactly like reinvesting my first market stall rent in a new property. I watched my portfolio slowly grow through the ups and downs of the market, each gain making future gains larger. Earlier investments had more time to grow, just like earlier property purchases in Fable.

    The mechanics were identical. One used digital gold coins and the other used actual euros, but the pattern was the same.

    The feelings matched as well. Watching my actual portfolio grow felt like watching my property empire expand, with at some point that same “holy shit, this is actually working” feeling. Hitting €10,000 invested felt like buying my first major property, while hitting €100,000 felt like owning the castle. Different stakes, but a similar sensation about having built something that compounded while simultaneously seeing financial constraints loosening.

    Playing Fable helped my investing journey because I’d already experienced compound growth there. “Own productive assets”, “reinvest for acceleration”, and “time amplifies everything” weren’t abstract concepts anymore. They were patterns I’d already watched play out with pretend money, but now they were happening in real life.

    My brokerage app doesn’t have chickens to kick, though, which honestly is a serious loss.

    The Best Lessons Often Sneak Up On You

    I still replay Fable II almost every year, and I always start the same way: earn enough gold as fast as possible, buy that first property immediately, and start the compound growth cycle from day one.

    It’s become a ritual, but it’s also a reminder.

    Sometimes the most practical education comes from the least likely places. Sometimes it comes from a medieval fantasy world where you can kick chickens, seduce villagers, own taverns, and accidentally learn that cash flow beats combat skills.

    Fable II gave me something most investing books don’t: a reference point that made investing make sense and feel familiar when I finally started for real. I didn’t just learn that compound growth works, I’d seen it happen before. I didn’t just understand passive income conceptually, I experienced what it feels like when money comes in while you’re doing something else.

    My guess is that you probably also have your own version of this. Might’ve been a different game, a book, a summer job, or simply watching your parents teach you something that only made sense later. The source matters way less than realizing that a random experience suddenly becomes useful.

    So next time someone says video games are a waste of time, tell them yours taught you about compound growth and passive income. Not because it sounds impressive, but because it might actually be true.

    And if they don’t believe you? Tell them to buy a vegetable stall in Albion and report back in a year.